
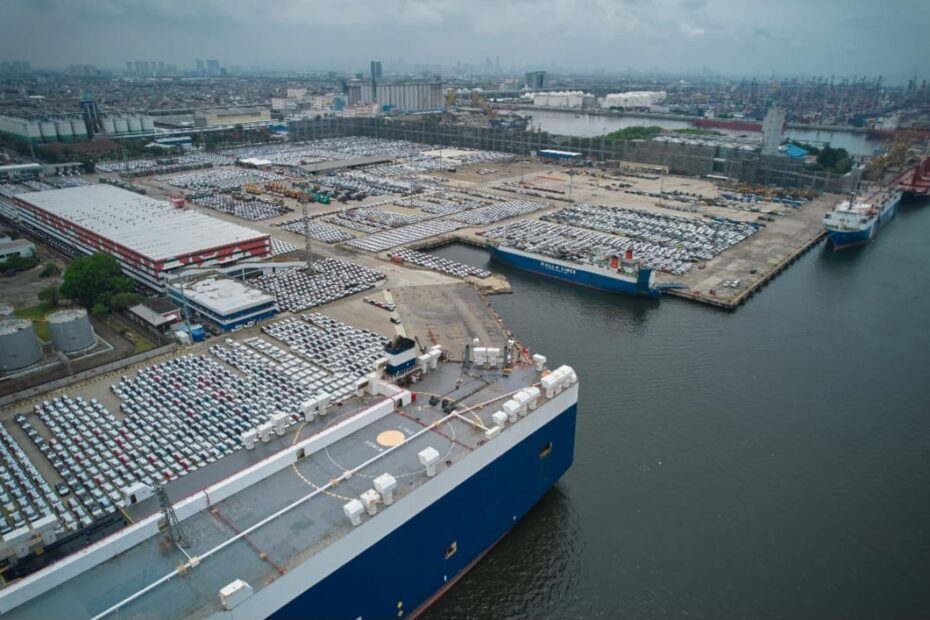
While the national automotive sector faced a downturn in early 2025, PT Indonesia Kendaraan Terminal Tbk (IDX: IPCC) bucked the trend, posting impressive growth in both revenue and profit for the first quarter of the year.
In its latest financial disclosure to the Financial Services Authority (OJK) and the Indonesia Stock Exchange (IDX), the Indonesia’s leading car terminal operator reported a 15.73% year-on-year increase in revenue, reaching IDR 203.27 billion. Net profit soared by 33.3% to IDR 51.17 billion – an exceptional result considering the broader industry context.
According to data from Gaikindo, Indonesia’s wholesale vehicle sales declined by 5.1% during the same period, making IPCC’s performance a notable outlier in the sector.
The company attributed much of its strong performance to its core business: handling Completely Built-Up (CBU) vehicles. This service segment alone grew by 14.78% year-on-year and accounted for the majority of IPCC’s revenue.
International services contributed approximately 80% of total income, with domestic operations making up the remaining 20%. By cargo type, CBU vehicle handling dominated revenue generation at 75%, followed by trucks and buses (10%), heavy equipment (8%), general cargo and spare parts (5%), and other cargo (1%).
Supporting these results were ongoing operational enhancements, including the implementation of digital systems like PTOS-C at both international and domestic terminals in Jakarta and the PRAYA financial platform.
Additionally, IPCC continued to refine its commercial strategy and expand value-added services such as the Pre-Delivery Center (PDC), Port Stock management, and Vehicle Processing Center (VPC) operations.
“This shows that our business diversification and operational efficiency strategies are working,” said IPCC President Director Sugeng Mulyadi in a statement on Monday (April 28, 2025).
“We’re not only earning revenue from vehicle logistics but also from supporting services such as land, building, water, and electricity management.”
Investor Confidence and Financial on the Rise
Investors responded positively to the Q1 report, with IPCC’s stock price climbing 7.74% since the beginning of 2025. Key financial indicators further underscored the company’s improving profitability: earnings per share (EPS) increased from IDR 21.11 to IDR 28.14, while the net profit margin rose to 25.2% from 21.9%. The EBITDA margin also grew to 43.4%, reflecting strong operational performance.
“This is a breath of fresh air for investors,” Mulyadi added. “Our commitment to transformation, digitalization, and long-term sustainability is beginning to show real returns.”
He also noted that favorable macroeconomic conditions, such as a 6.93% rise in exports and a 5.34% increase in imports (according to Indonesia’s Central Statistics Agency), are helping to support IPCC’s growth trajectory.
Solid Foundation for Future Expansion
In terms of financial position, IPCC maintained a strong balance sheet. Total assets rose by 3.11%, reaching IDR 1.89 trillion by March 2025, up from IDR 1.84 trillion at the end of 2024. Current assets also saw a healthy boost, increasing 7.56% to IDR 974.29 billion.
Looking ahead, IPCC is setting its sights on future expansion, particularly in the eastern regions of Indonesia. The company is preparing to develop new vehicle terminal facilities in Surabaya and Lembar (Lombok), aimed at strengthening national logistics connectivity.
“Our goal is to create a network of connected terminals that reduce logistics costs and enhance operational efficiency,” Mulyadi said.
IPCC is also positioning itself to ride the wave of Indonesia’s growing electric vehicle (EV) market. With more EV brands entering the country and a national EV ecosystem taking shape, the company expects to handle more than 70,000 vehicle units by the end of 2025.